Blog

  • Southern Apples: The Long History of Production and the New Era of Marketing

    Southern Apples: The Long History of Production and the New Era of Marketing

    Apples are often viewed as a perennial crop commonly produced for fresh consumption in the Northeast and Pacific Northwest. However, Southern apple orchard production has a history that begins with the earliest settlers in Virginia around 1622 (Flynt, 2023). As heterozygous plants, each apple seed is a blend of parent tree genetics which spurs completely new varieties. In the South, these new varieties flourished for much of the country’s history until the early 1900’s when commercial apple production expanded in the Pacific Northwest. While apples in the South were used for eating raw, many were processed into an alcoholic beverage called hard cider. Much like wine, apple varieties have distinct flavor attributes that contribute to the taste and marketing abilities of hard cider. 

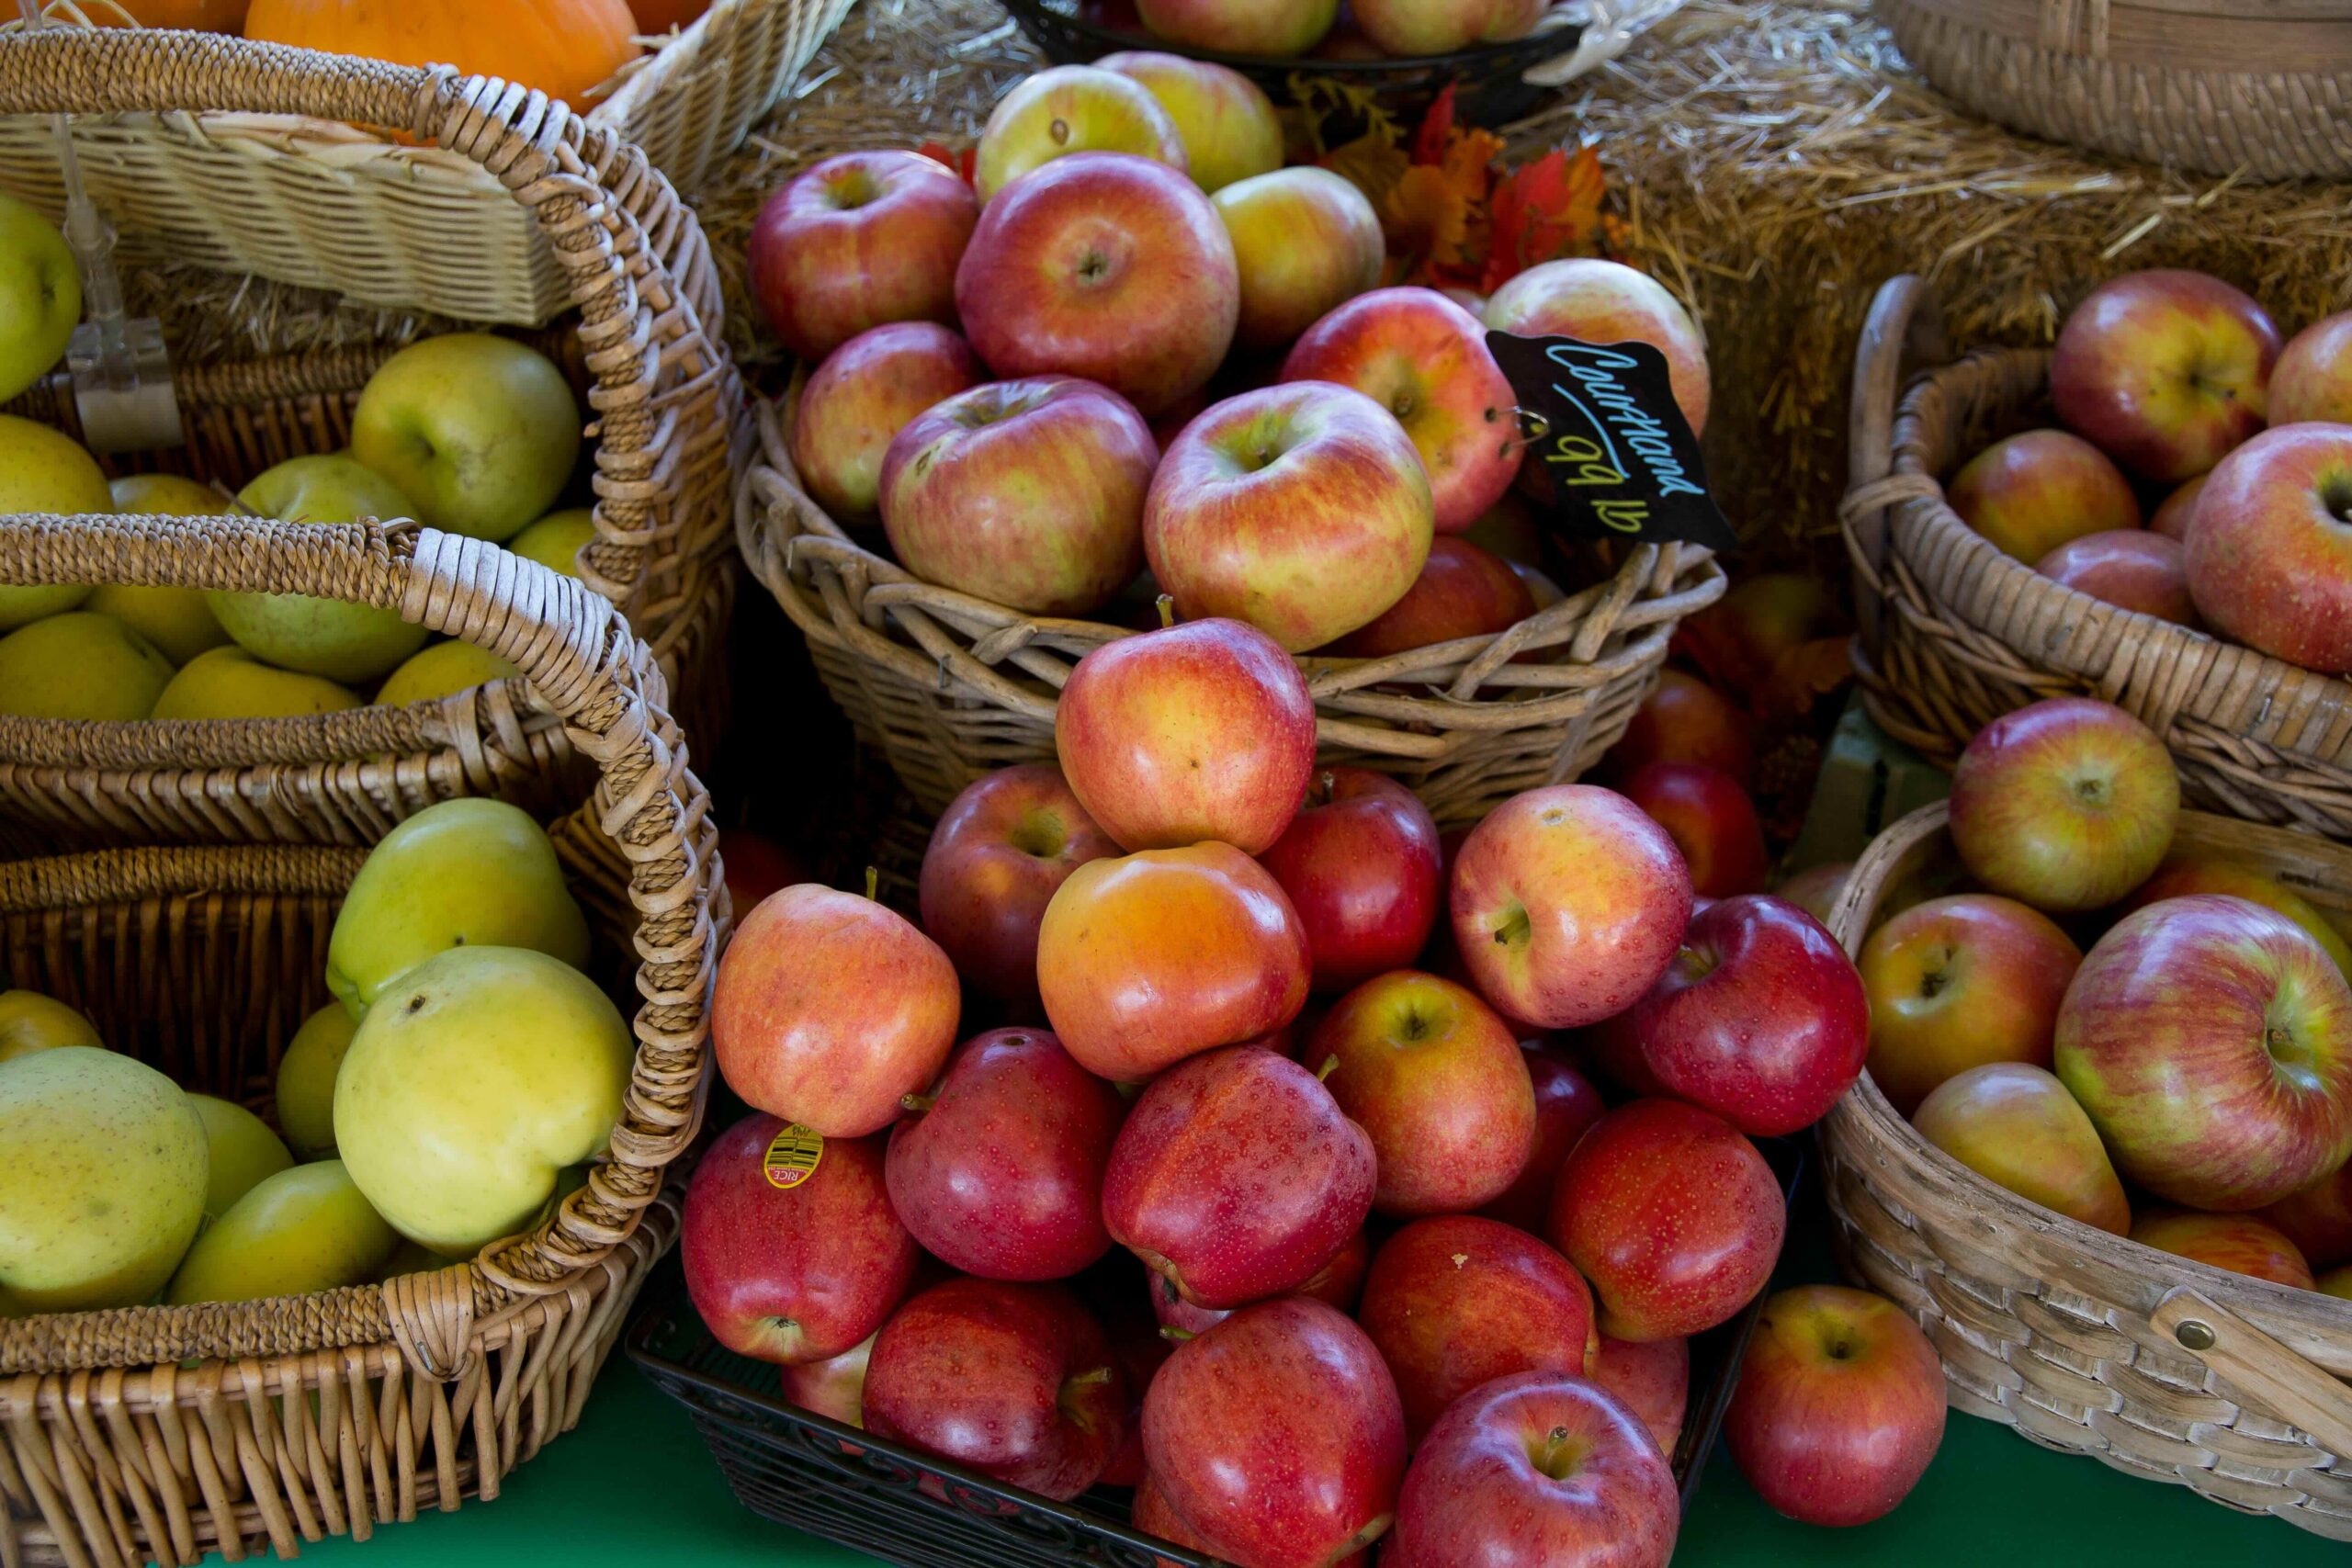
    After a decline in cider production and consumption that occurred during prohibition in the 1920s, production of Southern apples became a small part of agricultural productivity. However, the last 20 years have seen a renewed interest in craft, hard cider production and the revival of southern apples varieties such as Queen Pippin shown in Figure 1. Yet, marketing has long been difficult given the unknown identity of this beverage in the larger marketplace to consumers who are largely unfamiliar with the product. Recent research has shown that consumers are interested in hard cider and associate it as a complement to wine (Neill et al., 2024). By using consumer-oriented flavor language and co-marketing with wine, hard cider and southern apple production has the potential to return to its storied past with vigor. 

    Figure 1: Example of a Historical Southern Apple Variety that was Rediscovered and Being Produced in Commercial Orchards

    (Source: North Carolina Historic Sites, Horne Creek Farm, Southern Heritage Apple Orchard; Available online at: https://historicsites.nc.gov/all-sites/horne-creek-farm/southern-heritage-apple-orchard/learn-more/apple-variety-information/apple-index-q)

    Funding Statement: This work was supported by the USDA-NIFA AFRI under Grant #2020-68006-31682.


    References: 

    Flynt, Diane. 2023. Wild, Tamed, Lost, Revived: The Surprising Story of Apples in the South. UNC Press Books. 

    Neill, C. L., Lahne, J., Calvert, M., and Hamilton, L. (2024). Contextualizing hard ciderflavor language and market position. Journal of Wine Economics, 1–20. https://doi.org/10.1017/jwe.2024.13

  • Paved with Good Intentions: Unintended Impacts of Farm Bill Payment Limitations

    Paved with Good Intentions: Unintended Impacts of Farm Bill Payment Limitations

    While this may come as a surprise to some of our readers, farm program payment limits have been around almost as long as farm bills themselves. Modern payment limits are rooted in the Agricultural Act of 1970, but the earliest versions appeared in the Agricultural Adjustment Act of 1938, the nation’s second farm bill. While payment limits are not a new phenomenon, recent times have seen a sharp increase in the complexity – and perhaps unintended consequences – of the rules enforcing them.

    Applying payment limits to Federal farm programs might seem relatively straightforward, but the decades-long debate over who should be eligible for assistance – and once they are deemed eligible, how much assistance they should receive – has resulted in a morass of regulations that are almost impossible for even the most astute attorney to follow. For example, with respect to eligibility, the Federal government devotes hundreds of pages to simply identifying who is “actively engaged in farming” and in determining whether a farmer’s income exceeds allowable thresholds for participation. While the intent (i.e., making sure the farm safety net is only accessible to those who really need it) may be laudable, we argue that the execution has made both risk management and farm transitions unnecessarily more challenging for family farms.

    In a recent article in the Drake Journal of Agricultural Law, we explored all of these topics, focusing on one element in particular: the 2008 Farm Bill’s treatment of individuals and legal entities for purposes of applying payment limitations. According to the 2008 Farm Bill, both individuals and legal entities may only qualify for a single payment limit. The “legal entities” implicated by this provision include limited liability companies (LLCs) and corporations, both of which are restricted to a single payment limit regardless of the number of members of the farming operation that individually qualify as eligible for payment limits. This is in sharp contrast to the treatment of general partnerships, which may, in effect, combine the payment limits of their individual partners. As a practical matter, family farming operations comprised of multiple stakeholders must structure as general partnerships or some other form of joint venture if they are to avoid being forced into a single payment limit (Figure 1).

    While this all may seem rather academic, it matters a great deal to those who rely on farm programs to manage the risks they face in production agriculture. For example, a family farm with multiple stakeholders actively engaged in the farming operation may have been advised by their attorney or accountant to structure as a pass-through LLC (to manage risk or tax liability); unbeknownst to them, their entire farming operation was then subjected to a single payment limit. Perhaps more importantly, LLCs are a very popular legal vehicle for facilitating farm transitions, yet Federal treatment of LLCs for payment limit purposes significantly disincentives their use. Ironically, in the same farm bill that Congress uses to authorize risk management tools for farmers and ranchers, the payment limit rules continue to expose real-life farmers and ranchers to even more risk.

    In the article noted above, we argue for taking what we call an “entity agnostic” approach to farm bill payment limitations. Under this approach, any entity (especially pass-through entities like LLCs) involving two or more individuals would be treated like a partnership, where the number of payment limits parallels the number of actively engaged participants. This change would not affect who is eligible for assistance (although those rules are ripe for modernization as well). As we argue in the article, the remaining “eligibility rules provide more than adequate safeguards to ensure those receiving farm bill payments are legitimately involved with their respective farming operations.”

    Congress has an opportunity in the impending farm bill debate to help facilitate farm transitions from one generation to the next by modernizing payment limitations to ensure they are not disincentivizing the use of LLCs.  If you would like to read more on this topic—or if you are having trouble falling asleep tonight—considering checking out the full, 60-page article at this link.

    Figure 1. Comparing the Disparate Application of Payment Limits for LLCs and General Partnerships under Current Law.

    Source: https://aglawjournal.wp.drake.edu/wp-content/uploads/sites/66/2024/04/Ferrell-Ready-for-Publish.pdf

    Ferrell, Shannon L., Tiffany Dowell Lashmet, and Bart L. Fischer. “Paved with Good Intentions: Unintended Impacts of Farm Bill Payment Limitations.Southern Ag Today 4(19.4). May 9, 2024. Permalink

  • New Poultry Contracting Regulation’s Potential Effects on Broiler Growers

    New Poultry Contracting Regulation’s Potential Effects on Broiler Growers

    The USDA’s Transparency in Poultry Grower Contracting and Tournaments ruling became effective on February 12, 2024. This ruling modifies the Packers and Stockyard Act by adding several additional requirements to be met by “Live Poultry Dealers,” or what most contract growers know as integrators or poultry companies. The rule requires integrators to provide two disclosure documents: The “Live Poultry Dealer Disclosure Document” and the “Tournament Specific Input Disclosure.” A fact sheet covering the rule and its requirements can be found here: https://www.ams.usda.gov/sites/default/files/media/PoultryGrowerFactSheet.pdf

    The USDA also has a webinar that goes into further detail about the rule:  https://www.youtube.com/watch?v=ndz_gw4dpfM   In this webinar, USDA states that they expect implementation to evolve for each company as they make changes to comply, and they will work with companies to assist in compliance. 

    One of the requirements of interest is for integrators to guarantee an absolute minimum number of flocks per year and a minimum number of birds placed, or pounds of birds produced, per year on the contract grower’s farm. The results of this part of the ruling could be both positive and negative for growers. 

    On one side there is the contract broiler grower who has invested a large amount of capital to build a farm. A new broiler farm consisting of four 54’ x 500’ barns can cost $2 million or more to build and get ready for birds. The grower then must cover the utility and labor cost of growing the birds, both of which are steadily increasing. With interest rates above 7% currently, a grower would face over $400,000 in annual costs for his loan and expenses. This makes any form of income guarantee important to growers, as well as lenders. Before the new ruling, the best information available was company-provided estimates for grower income based on averages over time. The new ruling requires companies to guarantee a minimum number of birds per flock and flocks per year but not flock payments or final gross revenue. Under typical competitive pay programs, final flock payments are affected by bird growth, which is affected by on-farm management and cannot be guaranteed. Thus, the final flock payment to a specific farm could still vary significantly from company averages and is unknown until the end of the flock. This kind of income risk can make farm budgeting difficult and can drive growers to a defensive cost-saving posture as their only predictable form of income protection. Such cost-saving management decisions can negatively impact the birds’ performance and decrease the income potential for the grower and increase cost of production for the company. In such cases, a guarantee of income could be beneficial if it were sufficient to cover all or most known cash flow needs. Some companies had begun implementing modified pay programs with some income guarantees before this ruling came out. 

    On the company side, the placement guarantee rule leaves out the biological variability of producing broilers. There is an old saying, “don’t count your chicks before they hatch.” Poultry companies must plan months ahead and “count the chicks” before the eggs are laid. Sometimes, these expectations are not met for uncontrollable biological reasons, and there just aren’t enough chicks to go around. There is no language in the ruling that takes this into consideration. 

    There is also no language that addresses problems that can and do occur at the farm and company level that could interrupt timely placement and affect a farm’s number of flocks placed per year – whether that be planned, like plant maintenance or holidays, or unavoidable, like an HPAI outbreak. Sometimes, individual farms must perform maintenance or repair damage that would delay flock placement for several days or longer on that farm. Sometimes, integrators may need to respond to market downturns with placement changes. Such situations would typically only affect a percentage of a company’s broiler growers and only for a short time as well, though longer impacts have been known to occur in times of severe market struggles, like what happened with COVID-19. If the timing of any of these situations were right, they may keep an affected farm from getting the stated minimum number of flocks in one year.  

    These real-world situations may result in companies not contractually guaranteeing what they normally may expect growers to receive, nor what they desire to process through the plant, but instead guaranteeing significantly less to avoid running afoul of the rule. This makes obvious sense and protects the company, but creates additional problems for the grower, especially when it comes to securing financing for new facilities. There is a significant possibility that financial institutions would only be able to calculate income potential generated from the guaranteed minimums. Such a decreased income could hinder growers from obtaining loans. 

    Another important requirement is that companies must provide average grower revenue numbers per square foot by housing type, low to high by quintile, and across time. These could be used as a basis of income for financial determinations. It could be argued that, except for house type and quintile breakdown, this is the same as the overall average gross returns that integrators have been providing in pro forma documents before the ruling. The biggest difference is that this would give potential growers a snapshot of what pay could be, both high and low, and how it can vary rather than a single-point average. The problem is that under typical competitive pay programs now, grower income is subject to change for every flock. Therefore, a farm could and likely will fall within each of the quintiles at some point in time. Therefore, if a grower was wanting to estimate revenue based on the least risk, he would be forced to only consider the lowest quintile pay as his basis for a decision. This conservative evaluation may project an artificially negative outlook on starting a poultry farm both for growers and financial institutions.  


    Brothers, Dennis. “New Poultry Contracting Regulation’s Potential Effects on Broiler Growers.Southern Ag Today 4(19.3). May 8, 2024. Permalink
  • Mixed Impacts of H5N1 in Dairy Cows on Dairy and Beef Cattle Markets

    Mixed Impacts of H5N1 in Dairy Cows on Dairy and Beef Cattle Markets

    Over the past several weeks, H5N1 (i.e., highly pathogenic avian influenza) affecting U.S. dairy herds has been making news. The most recent came last week when the USDA ordered that lactating dairy cows must be tested for H5N1 before being transported across state lines (USDA-APHIS, 2024) and the FDA reported finding remnants of the H5N1 virus in commercial milk supplies (US FDA, 2024). Importantly, officials state that milk and beef products remain safe.

    Amid this market shock, futures price fluctuations for the dairy sector have been relatively small. Class III milk futures saw no significant price swings with March news reports, and prices on April 25 jumped by around 2.5 percent for the May contract potentially in response to lower production expectations. However, prices changed by similar or larger magnitudes five previous days since April 5. It is unclear if that price change was in line with general market uncertainty or due to the announcement.

    In contrast, both feeder cattle and live cattle contracts saw large price drops during March news events. For example, June live cattle contracts dropped by nearly 2.75 percent the day a human case of H5N1 was reported. However, live cattle and feeder cattle prices moved higher on April 25.

    For dairy markets, two things may be happening at the same time to create a relatively steady price situation. Supply may be dropping (due to lower milk production) while potential consumer fears reduce demand. In tandem, this could create relatively constant prices, but production and disappearance would drop. Production and disappearance data to support this should become available in the coming months.

    For cattle markets, the main effect appears to be speculative consumer concerns that would drive down beef demand, thus reducing the value of cattle. This has materialized to a certain extent as Colombia banned imports of U.S. beef into the country. However, the price reaction on April 25 that saw prices move higher suggest that these initial fears may be short-term.

    As more data and news come out, markets’ reactions may change. This area should be closely watched, especially given the tight supplies in the beef cattle market and production uncertainty in milk markets.

    Figure 1: Nearby Contract Prices for Cattle and Milk Futures

    Source: CME Group & LMIC

    Sources: 

    US FDA. (2024, April 23). Updates on Highly Pathogenic Avian Influenza (HPAI)https://www.fda.gov/food/alerts-advisories-safety-information/updates-highly-pathogenic-avian-influenza-hpai

    USDA-APHIS. (2024, April 24). Federal Order Requiring Testing for and Reporting of Highly Pathogenic Avian Influenza (HPAI) in Livestockhttps://www.aphis.usda.gov/sites/default/files/dairy-federal-order.pdf


    Secor, William. “Mixed Impacts of H5N1 in Dairy Cows on Dairy and Beef Cattle Markets.” Southern Ag Today 4(19.2). May 7, 2024. Permalink

  • Public Information and the Variability of U.S. Cotton Production Forecasts

    Public Information and the Variability of U.S. Cotton Production Forecasts

    During April, the USDA National Agricultural Statistics Service (NASS) announced the suspension of selected statistical reports and processes, including the annual objective yield sampling effort for U.S. cotton.  The latter was a process of field sampling of squares and bolls in major cotton producing states, from which an objective estimate of yield was calculated.  This estimate presumably informed the monthly U.S. cotton production forecasts, beginning with the August forecast, with potential to confirm or contradict the earlier (May, June, July) forecasts that are traditionally based on historical average yield and abandonment, along with subjective opinion.  It should be noted that in 2019, the start date for objective yield sampling for most of the U.S. was moved from August to September. 

    The delaying of the objective yield survey process, followed by its announced elimination, has potential for increasing the forecasting error of U.S. cotton production, which has implications for market planning and even price volatility.  Figure 1 provides a description of the variability of USDA NASS monthly forecasts of U.S. cotton, by crop year.  For example, the year 2012 in Figure 1 graphs the standard deviation (roughly 200,000 bales) around the average of forecasted cotton production from the May 2012 initial monthly forecast through the following April (2013) forecast of 2012 cotton production.  

    The graphed points in Figure 1 represent the variation associated with revised production estimates.  Through 2018, the public data collection and publication of information to inform the production estimates was the same.  Over this period, the variability of those monthly estimates within a given crop year fluctuated between 200,000 and one million bales around the average production for that year.  This appears as a fairly narrow, sideways pattern.  

    Since 2019, there has been a marked increase in variability of the monthly production forecasts around average crop year production for the last five years.  This variability reached 1.7 million bales in 2020, and 1.6 million in 2023. The increase in production forecast variability since 2019 is visually correlated with the delay of objective field sampling for most of the U.S. Cotton Belt until September.  It is unknown whether there is any causal influence.  However, the complete elimination of cotton objective yield sampling represents an even larger disruption of previously available information.  Our hypothesis is that confirming information on the size of the U.S. crop will have to wait until data from NASS surveys of ginning, as well as bale counts from USDA classing offices, are finalized in the winter. The absence of in-season, objective yield information adds to market uncertainty with likely price implications. 

    Figure 1. Standard Deviation of Monthly U.S. Cotton Production Forecasts (May to April), By Crop Year.

    Robinson, John. “Public Information and the Variability of U.S. Cotton Production Forecasts.Southern Ag Today 4(19.1). May 6, 2024. Permalink